A promising Gilbert rental is more than a home with an attractive asking price. Compare realistic rent, vacancy, operating costs, financing, and rental restrictions before deciding whether the numbers support your goals. A simple cash-flow model can also show how much room you have for unexpected repairs or a slower leasing period.
Start With the Property, Not the Projection
A rental purchase begins with two questions: What could this home reasonably earn, and what will it cost to own? In Gilbert, the answer can vary from one property to another based on its condition, floor plan, amenities, and proximity to daily conveniences. A useful analysis treats every estimate as a starting point to verify—not a promise of future income.
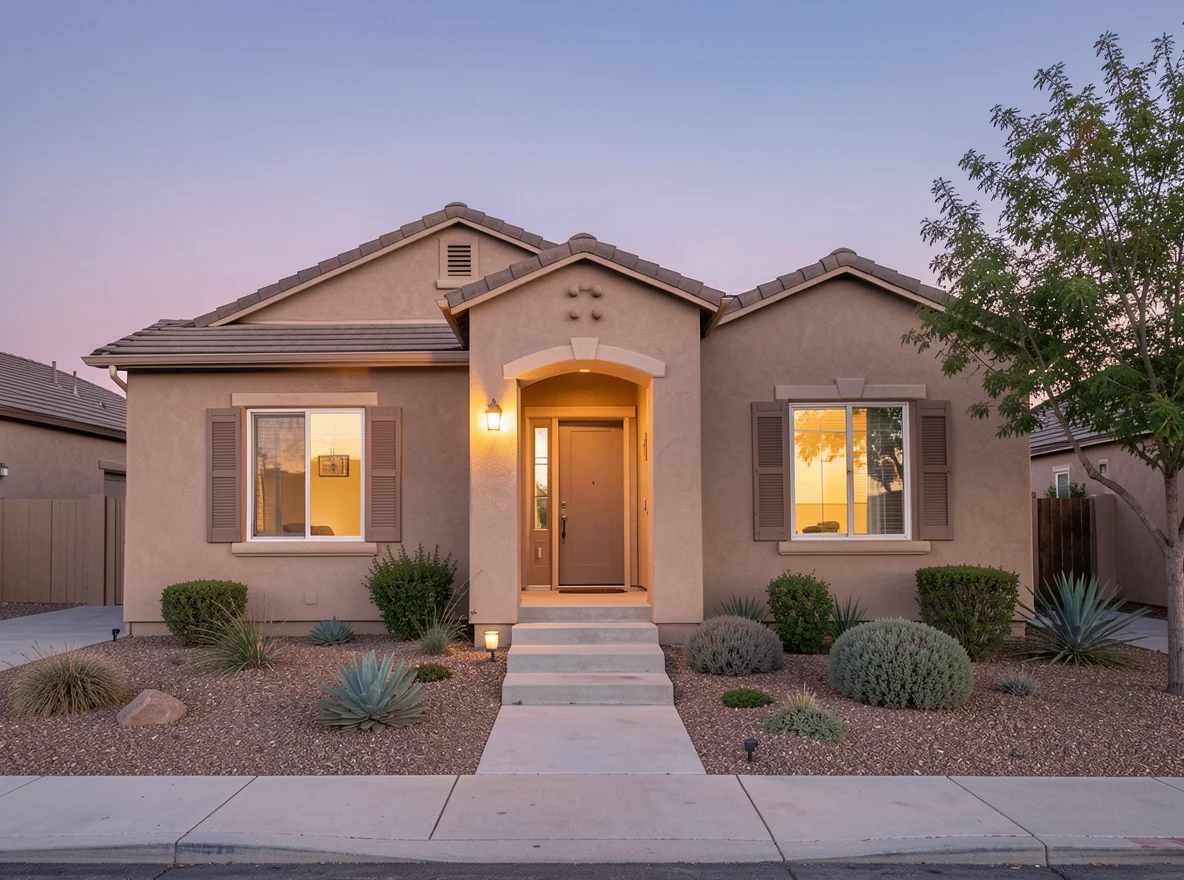
Begin by identifying your intended rental strategy. A long-term lease and a short-term rental have different operating costs, management demands, and rules. Decide how involved you want to be, how much cash you can set aside, and whether you are looking primarily for monthly income, potential long-term appreciation, or a combination of both.
Next, consider the features a prospective renter can assess directly: the number of bedrooms and bathrooms, parking, storage, outdoor space, appliance condition, and access to parks, dining, and major routes. Compare those features with competing rentals rather than assuming every improvement will translate into higher rent. A pool, for example, may distinguish a home but also adds maintenance and insurance costs.
It is equally important to review the property’s age and condition. A lower purchase price may look appealing until an inspection reveals an aging roof or air-conditioning system. In Arizona’s heat, cooling equipment deserves particular attention. Ask for available service records and use qualified inspectors to help estimate near-term work.
Build a Defensible Rent Estimate
Look for recent, comparable rentals in Gilbert with similar square footage, bedroom and bathroom counts, condition, and lease terms. Active listings show what owners are asking; completed leases, when available, offer a better indication of what renters actually agreed to pay. Compare several properties, and note how long listings have been available when that information can be verified.
Adjust your estimate for meaningful differences. A renovated kitchen, covered parking, or included landscaping service may affect the comparison, while an older interior or a less convenient layout may pull the likely rent in the other direction. Avoid relying on the highest advertised price: a property sitting vacant while you seek an ambitious rent can reduce annual income.
At $2,500 per month, one vacant month reduces scheduled annual rent by $2,500 before you pay for cleaning, repairs, or leasing costs.
Run at least three scenarios: a conservative rent with more vacancy, a middle estimate supported by comparable leases, and a stronger outcome. Ask a local property manager about current leasing conditions and typical management fees, then refresh your estimates before making an offer. Rental demand and available inventory can change, so yesterday’s comparison is not a guarantee of tomorrow’s result.
Account for the Costs of Ownership
Scheduled rent is not profit. Start with annual rent, subtract an allowance for vacancy and uncollected rent, and then list the operating expenses you expect to pay. Use property-specific quotes and documents whenever possible instead of relying on a generic percentage.
Typical expenses include property taxes, landlord insurance, HOA dues, routine maintenance, landscaping, pest control, and any utilities the owner pays. If you hire a manager, include management, leasing, and renewal fees. Even if you plan to handle the work yourself, consider the time and possible future cost of outsourcing it.
Set aside money separately for larger capital expenses, such as replacing an air conditioner, roof, or appliances. These items may not occur every year, but ignoring them can make a property appear more profitable than it is. Obtain insurance quotes before committing; coverage and premiums can differ from those for an owner-occupied home.
Taxes and fees also require property-specific review. Confirm the current assessment, expected insurance cost, HOA charges, and any applicable rental registration or tax requirements. A tax professional can explain how your ownership structure and circumstances affect the after-tax result; this analysis is not a substitute for individualized tax advice.
Compare Cap Rate and Cash-on-Cash Return
Two common measures answer different questions. Net operating income, or NOI, is rental income after vacancy and operating expenses, before mortgage payments and income taxes. Dividing NOI by the purchase price gives the capitalization rate, a way to compare properties without factoring in financing. It does not capture every cost or risk.
Here is an illustrative example, not a current Gilbert market estimate. Suppose a $400,000 property rents for $2,500 a month. Scheduled annual rent is $30,000. After a 5% vacancy allowance of $1,500 and $10,500 in annual operating expenses, NOI is $18,000. Dividing $18,000 by $400,000 produces a 4.5% cap rate.
Now add financing and a capital reserve. If annual mortgage payments are $15,000 and you set aside $1,800 for future major replacements, annual cash flow is $1,200 before income taxes. If your total cash invested—including down payment and closing costs—is $120,000, the cash-on-cash return is 1%: $1,200 divided by $120,000. Actual loan terms, expenses, and results will differ.
Cap rate excludes mortgage payments; cash-on-cash return incorporates financing and the cash you invested. Calculate both before comparing properties.
Neither measure guarantees appreciation or accounts for every tax consequence. Test what happens if rent is lower, insurance rises, or a major repair arrives sooner than expected. Also discuss financing options with a lender: investment-property rates, down payments, reserves, and qualification requirements may differ from those for a primary residence.
Verify Rental Rules Before You Commit
Before assuming a home can be rented the way you intend, review the HOA’s governing documents and any rental restrictions, approval procedures, minimum lease terms, or fees. Check current town and state requirements, especially if you are considering a short-term rental. Rules can change, and listing remarks alone are not a substitute for the governing documents or confirmation from the relevant authorities.
For a long-term rental, budget for a written lease, consistent application procedures, maintenance response, and compliance with fair housing and landlord-tenant laws. An Arizona real estate attorney or qualified property manager can help you understand obligations and put a practical operating plan in place.
Make the Decision With Room for Surprises
A sound purchase is one whose numbers still make sense when conditions are less favorable than hoped. Compare your assumptions across several homes, keep a reserve beyond your closing costs, and consider how long you can comfortably hold the property. If you are ready to evaluate a specific Gilbert listing, Emily Laufer can help you examine the property and local comparisons while you consult your lender, inspector, and tax adviser on the details.